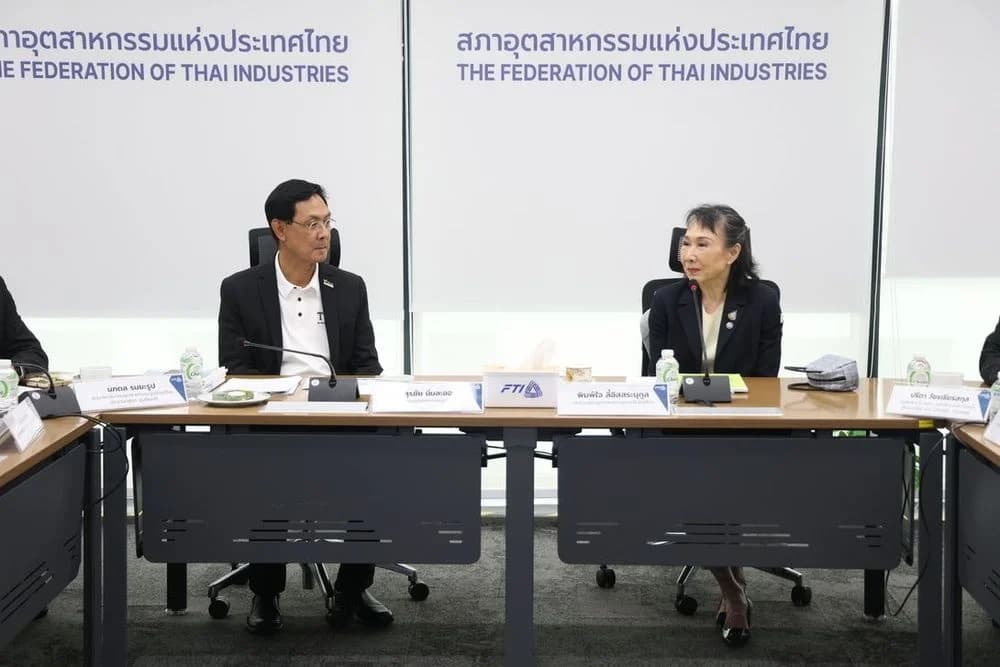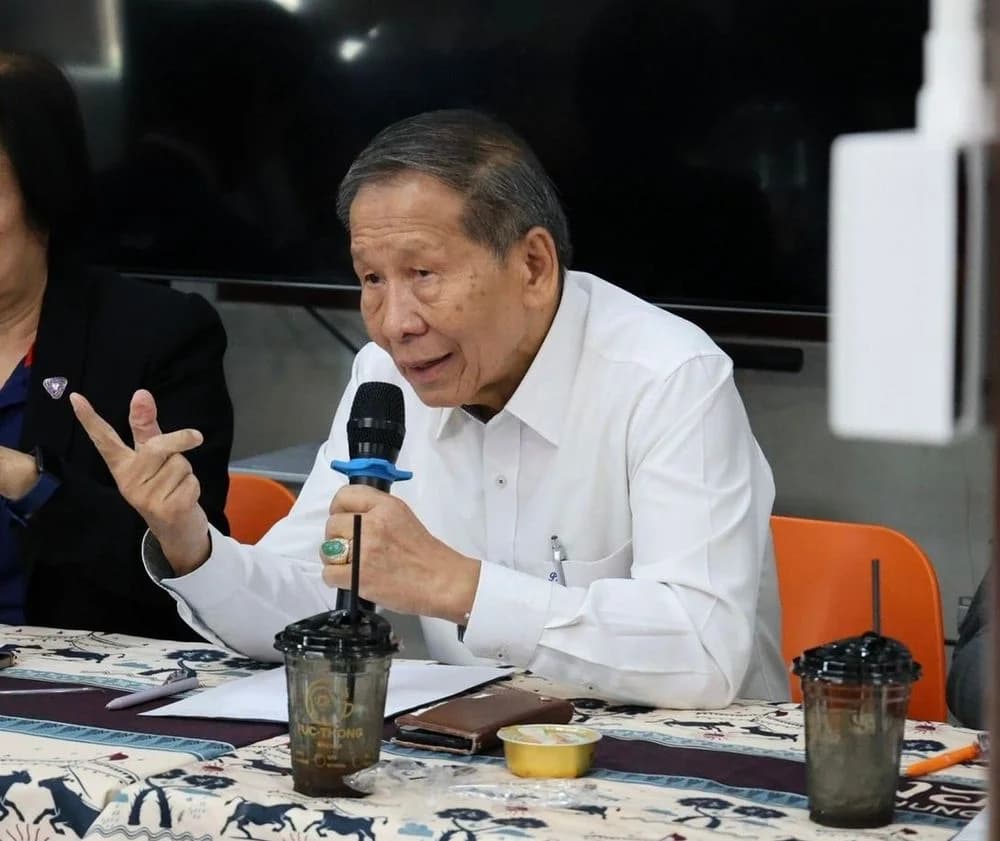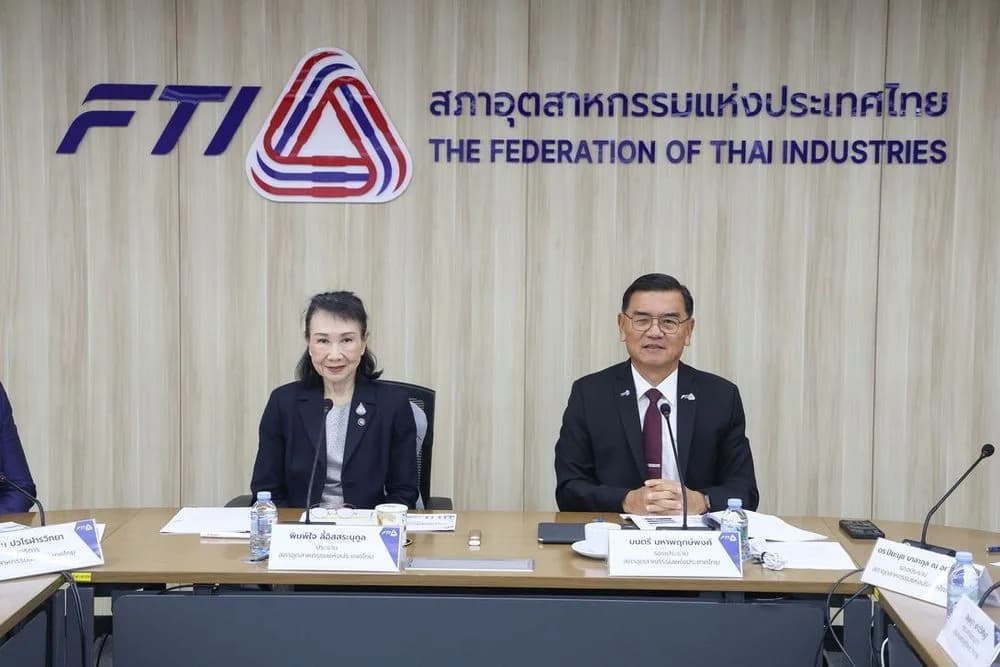
วันพุธที่ 2 กันยายน 2569 นายผยง ศรีวณิช ประธานสมาคมธนาคารไทย เป็นประธานการแถลงข่าว คณะกรรมการร่วมภาคเอกชน 3 สถาบัน (กกร.) โดยมีนางพิมพ์ใจ ลี้อิสสระนุกูล ประธานสภาอุตสาหกรรมแห่งประเทศไทย(ส.อ.ท.) และนายอธิป พีชานนท์ รองประธานกรรมการสภาหอการค้าแห่งประเทศไทย ร่วมในการแถลงข่าว ณ โรงแรมโกลเดน ทิวลิป ซอฟเฟอริน กรุงเทพฯ
เศรษฐกิจไทยปี 69 มีแนวโน้มเติบโตดีกว่าที่ประเมินไว้ จากแรงส่งของการส่งออกและการลงทุนภาคเอกชนที่ขยายตัวสูงกว่าคาด โดย กกร. ปรับเพิ่มคาดการณ์การส่งออกเป็น 12%-16% จากเดิม 8%-10% และ ปรับประมาณการ GDP เป็น 2.1%-2.5% จากเดิม 1.6%-2.0%
ปัญหาความขัดแย้งในตะวันออกกลางที่กลับมายกระดับ เพิ่มแรงกดดันต่อราคาพลังงานโลกและสร้างความผันผวนในตลาดการเงิน โดยล่าสุด ณ ต้นเดือน ก.ย. 69 ราคาน้ำมันดิบในตลาดโลกปรับเพิ่มขึ้นแตะ 95 ดอลลาร์สหรัฐฯ/บาร์เรล (จาก 84 ดอลลาร์ฯ/บาร์เรลเมื่อเดือน ก.ค.) ท่ามกลางปริมาณน้ำมันสำรองโลกที่ลดลงต่อเนื่อง ขณะเดียวกัน จากมาตรการจำกัดการส่งออกน้ำมันดีเซลที่ส่งผลให้เกิดภาวะน้ำมันสำเร็จรูปสะสมในคลังสูงขึ้น จนผู้ประกอบการโรงกลั่นจำเป็นต้องลดกำลังการผลิตลง ส่งผลกระทบต่อต้นทุนการกลั่นและปริมาณวัตถุดิบพลอยได้จากกระบวนการกลั่น (By-products) อาทิ Naphtha, Benzene, Toluene, Para-Xylene เป็นต้น ซึ่งเป็นวัตถุดิบสำคัญของอุตสาหกรรมปิโตรเคมี พลาสติก ยาง เคมีภัณฑ์ ยานยนต์ และบรรจุภัณฑ์ ดังนั้น จึงเสนอให้รัฐบาลเร่งพิจารณาผ่อนคลายให้สามารถส่งออกน้ำมันได้ตามกลไกการค้าเสรี รวมทั้ง การบริหารสถานการณ์ร่วมกันระหว่างภาครัฐและเอกชน ตามที่ กกร. ได้เสนอไปก่อนหน้านี้ ซึ่งจะเป็นแนวทางสำคัญในการบริหารสมดุลการผลิต ลดผลกระทบต่อภาคการกลั่น และรักษาความต่อเนื่องของห่วงโซ่อุปทานอุตสาหกรรมไทย
กกร. มองเห็นความสำคัญในการยกระดับข้อมูลอุตสาหกรรมของประเทศ เพื่อให้เข้าใจการเติบโตของเศรษฐกิจไทยในลักษณะ K-shape Economy มากขึ้น ซึ่ง กกร. ได้ติดตามประเด็น K-shape ของเศรษฐกิจไทยอย่างต่อเนื่องมาตั้งแต่เดือน มิ.ย. 69 โดยเจาะลึกข้อมูลด้านการส่งออก การผลิต และข้อมูลงบการเงินภาคธุรกิจ ทั้งในมิติรายอุตสาหกรรม สัญชาติและขนาดของธุรกิจ พบว่า K ขาบนกระจุกตัวในธุรกิจ New Economy ที่ได้อานิสงส์จาก Digital และ AI เช่น คอมพิวเตอร์และเซมิคอนดักเตอร์ ซึ่งส่วนใหญ่เป็นบริษัทจีน สหรัฐฯ และสิงคโปร์ ขณะที่ K ขาล่างเป็นธุรกิจที่เผชิญการแข่งขันรุนแรงจากสินค้าต่างประเทศ เช่น ยานยนต์ ปิโตรเลียม และวัสดุก่อสร้าง โดยในช่วง 5 ปีที่ผ่านมาพบว่าธุรกิจ SMEs ใน K ขาล่าง สัญชาติไทยที่อยู่ใน 7 อุตสาหกรรมภายใต้ “Reinvent Thailand” มีการผลิตลดลงเฉลี่ย 8% ขณะที่กิจการต่างชาติลดลงสูงถึง 19% โดยเฉพาะธุรกิจญี่ปุ่น ความแตกต่างที่เกิดขึ้นทำให้การมองเพียงตัวเลขเศรษฐกิจในภาพรวมอาจไม่เพียงพอ และยิ่งตอกย้ำความสำคัญของข้อมูล ผ่านการยกระดับตัวชี้วัดใน 3 มิติ ได้แก่ ความครอบคลุม (Coverage) คุณภาพข้อมูล (Quality) และสะท้อนโครงสร้างทางเศรษฐกิจ (Structure) ที่เปลี่ยนแปลงไป โดยอาศัยการเชื่อมโยงข้อมูลจากหลายหลายหน่วยงาน เช่น สำนักงานเศรษฐกิจอุตสาหกรรม สภาพัฒน์ และสำนักงานประกันสังคม เพื่อให้เกิดการปฎิรูปเชิงโครงสร้างอย่างเร่งด่วน
เศรษฐกิจไทยปี 69 มีแนวโน้มเติบโตดีกว่าที่ประเมินไว้ จากแรงส่งของการส่งออกและการลงทุนภาคเอกชนที่ขยายตัวสูงกว่าคาด โดย กกร. ปรับเพิ่มคาดการณ์การส่งออกเป็น 12%-16% จากเดิม 8%-10% และ ปรับประมาณการ GDP เป็น 2.1%-2.5% จากเดิม 1.6%-2.0% อย่างไรก็ดี แรงส่งจากการส่งออกและการลงทุนภาคเอกชนสู่เศรษฐกิจในประเทศลดลงอย่างชัดเจน โดยในอดีตการส่งออกที่เติบโตเฉลี่ยราว 14% และการลงทุนที่เติบโต 10% เคยสอดคล้องกับ GDP ที่ขยายตัวเฉลี่ยราว 6-7% สะท้อนว่าไทยสร้างมูลค่าเพิ่มในประเทศ (Domestic Value Capture) ได้น้อยลง จากการพึ่งพา Import Content ที่สูง ขณะที่การลงทุนระลอกใหม่ยังสร้างการจ้างงานได้จำกัดเมื่อเทียบกับในอดีต ทั้งนี้ไทยจำเป็นต้องรักษาการอยู่ในเรดาร์การลงทุนของโลก แต่ต้องเร่งต่อยอดให้เต็มศักยภาพ ตัวอย่างเช่น data center ซึ่งทุกการลงทุน 100 MW คิดเป็นมูลค่ากว่า 6 หมื่นล้านบาท ต้องเร่งสร้าง Ecosystem ให้เกิดเชื่อมโยงตั้งแต่ต้นน้ำถึงปลายน้ำ (vertical integration) อาทิ ขยายการลงทุน PCB ที่ได้รับการอนุมัติโดย BOI การลงทุนด้านโครงสร้างพื้นฐานพลังงานสะอาด น้ำ การยกระดับภาคอุตสาหกรรมไปสู่ smart manufacturing และการเตรียมความพร้อมด้านบุคคลากร โดยมีส่วนร่วมจากสถาบันการศึกษา ตลอดจนการใช้ประโยชน์จากข้อมูลอย่างเต็มศักยภาพเพื่อยกระดับอุตสาหกรรมใหม่ เช่น creative economy เพื่อให้เกิด real impact ต่อเศรษฐกิจในประเทศ ดังนั้น กกร. จึงได้แต่งตั้งคณะทำงาน Data center เพื่อร่วมขับเคลื่อนธุรกิจนี้ให้เกิดประโยชน์สูงสุดกับประเทศไทย
ประเทศไทยจำเป็นต้องเร่ง Reinvent เศรษฐกิจ เพื่อปลดล็อกข้อจำกัดเชิงโครงสร้างและปรับตัวรับโอกาสจากจังหวะที่ห่วงโซ่อุปทานโลกกำลังปรับเปลี่ยนครั้งใหญ่ สร้าง Trust & Confidence และดึงดูดการลงทุนระลอกใหม่ จึงเป็นที่มาของการจัดงาน “The Bangkok Business Summit 2026: Reinvent Thailand, Resilient ASEAN” ที่ กกร. และพันธมิตรในภาคส่วนต่างๆ มีความพร้อมที่จะเปิดเวทีสำคัญนี้ในวันที่ 3 กันยายน 2569 ณ ศูนย์การประชุมแห่งชาติสิริกิติ์ ซึ่งจะเป็นเวทีผนึกกำลังภาครัฐ เอกชน และองค์กรระหว่างประเทศ เพื่อร่วมกันขับเคลื่อนการปฏิรูปเศรษฐกิจไทยให้เกิดผลอย่างเป็นรูปธรรม โดยภายในงานจะมีการหารือถึง New Growth Engines ของประเทศ การยกระดับขีดความสามารถในการแข่งขัน การดึงดูดการลงทุนในอุตสาหกรรมแห่งอนาคต การพัฒนาโครงสร้างพื้นฐานและพลังงาน การเปลี่ยนผ่านสู่เศรษฐกิจคาร์บอนต่ำ ตลอดจนการสร้างเศรษฐกิจและภูมิภาคอาเซียนที่มีความยืดหยุ่นและพร้อมรับความเปลี่ยนแปลง และส่งผลดีอย่างทั่วถึงทั้งในมุม Supply chain, SMEs และเศรษฐกิจชุมชน
กรอบประมาณการเศรษฐกิจปี 2569 ของ กกร.
ปี 2568
GDP 2.4
ส่งออก 12.9
เงินเฟ้อ -0.1
ปี 2569
(ณ มิ.ย.- ส.ค. 69)
GDP 1.6 ถึง 2.0
ส่งออก 8.0 ถึง 10.0
เงินเฟ้อ 2.5 ถึง 3.0
ปี 2569
(ณ ก.ย. 69)
GDP 2.1 ถึง 2.5
ส่งออก 12.0 ถึง 16.0
เงินเฟ้อ 2.5 ถึง 3.0
ที่มา: สศช. พณ. และประมาณการโดย กกร.
On Wednesday, September 2, 2026, Mr. Payong Srivanit, Chairman of the Thai Bankers' Association, chaired a press conference for the Joint Private Sector Committee of three institutions (JPS), with Mrs. Pimjai Leeissaranukul, President of the Federation of Thai Industries (FTI), and Mr. Athip Peechannot, Vice Chairman of the Board of the Thai Chamber of Commerce, also in attendance at the Golden Tulip Sovereign Hotel, Bangkok.
The Thai economy in 2026 is expected to perform better than previously estimated, fueled by stronger export and private sector investment growth than anticipated. The JPS has revised its export growth forecast to 12%-16%, up from 8%-10%, and adjusted the GDP estimate to 2.1%-2.5%, an increase from the previous forecast of 1.6%-2.0%.
The escalating conflicts in the Middle East have intensified pressures on global energy prices, creating volatility in financial markets. As of early September 2026, global crude oil prices increased to 95 USD/barrel (up from 84 USD/barrel in July), amid continuing declines in global oil reserves. Concurrently, measures limiting diesel oil exports have resulted in a buildup of refined oil stocks, prompting refiners to reduce their production capacity, which impacts refining costs and the quantities of by-products from refining processes, such as Naphtha, Benzene, Toluene, and Para-Xylene—key raw materials for the petrochemical, plastic, rubber, chemical, automotive, and packaging industries. Therefore, the JPS proposes that the government expedite the consideration of relaxing oil export restrictions in accordance with free trade mechanisms, as well as manage the situation collaboratively between the public and private sectors, as previously suggested by the JPS. This will be a crucial approach to managing production balance, reducing impacts on the refining sector, and maintaining the continuity of the supply chain in Thai industries.
The JPS recognizes the importance of enhancing industry data in the country to better understand the growth of the Thai economy in a K-shape economic context. The JPS has been monitoring this K-shape issue in the Thai economy continuously since June 2026, delving into data on exports, production, and business financial information across industrial dimensions, nationality, and size. It was found that the upper part of the K is concentrated in new economy businesses benefiting from Digital and AI, such as computers and semiconductors, primarily held by companies from China, the United States, and Singapore. In contrast, the lower part of the K consists of businesses facing intense competition from foreign products, such as automotive, petroleum, and construction materials. Over the past five years, it has been revealed that SMEs in the lower K, Thai nationality operating in 7 industries under “Reinvent Thailand,” have seen production decrease by an average of 8%, while foreign enterprises have experienced a decline of as much as 19%, especially in Japanese businesses. This disparity emphasizes that merely viewing overall economic numbers may be insufficient and underscores the critical importance of data through the enhancement of indicators across three dimensions: coverage, data quality, and reflection of changing economic structure. This enhancement is facilitated by linking data from various agencies, such as the Office of Industrial Economics, the National Economic and Social Development Board, and the Social Security Office, to urgently implement structural reforms.
The Thai economy in 2026 shows a promising growth outlook beyond previous assessments, driven by stronger export and private sector investment growth. The JPS has increased its export forecast to 12%-16% from the previous estimate of 8%-10% and adjusted its GDP estimate to 2.1%-2.5% from 1.6%-2.0%. However, the momentum from exports and private sector investment towards the domestic economy has clearly decreased. Historically, average export growth of about 14% and an investment growth average of 10% aligned with GDP growth averaging around 6-7%, reflecting Thailand's reduced domestic value capture due to a high dependency on imported content. Additionally, the new wave of investment has limited employment creation compared to the past. Thus, Thailand must remain on the global investment radar but also rapidly enhance its potential. For instance, a data center investment of 100 MW equates to more than 60 billion baht, necessitating the rapid establishment of an ecosystem linking upstream to downstream (vertical integration), such as expanding investment in PCBs approved by the BOI, investments in clean energy infrastructure, water, upgrading industries towards smart manufacturing, and preparing human resources with contributions from educational institutions, as well as fully utilizing data to uplift new industries such as the creative economy for a real impact on the domestic economy. Therefore, the JPS has appointed a Data Center Task Force to drive this business forward for maximum benefit for Thailand.
Thailand must expedite the reinvention of its economy to unlock structural limitations and adapt to opportunities from the significant transformations occurring in the global supply chain, building trust and confidence to attract a new wave of investments. This leads to the organization of “The Bangkok Business Summit 2026: Reinvent Thailand, Resilient ASEAN,” where the JPS and partners from various sectors are poised to launch this significant platform on September 3, 2026, at the Queen Sirikit National Convention Center. This event aims to consolidate efforts between the public sector, private sector, and international organizations to collaboratively drive Thai economic reform into tangible outcomes. The summit will discuss the country’s new growth engines, enhancing competitive capabilities, attracting investment in future industries, infrastructure and energy development, transitioning to a low-carbon economy, and creating a resilient economy and region in ASEAN that is ready for change, positively impacting supply chains, SMEs, and community economies.
The economic forecast framework for 2026 as presented by the JPS:
For 2025
GDP 2.4
Exports 12.9
Inflation -0.1
For 2026
(as of Jun-Aug 2026)
GDP 1.6 to 2.0
Exports 8.0 to 10.0
Inflation 2.5 to 3.0
For 2026
(as of Sep 2026)
GDP 2.1 to 2.5
Exports 12.0 to 16.0
Inflation 2.5 to 3.0
Source: NESDB, Ministry of Commerce, and estimates by the JPS.